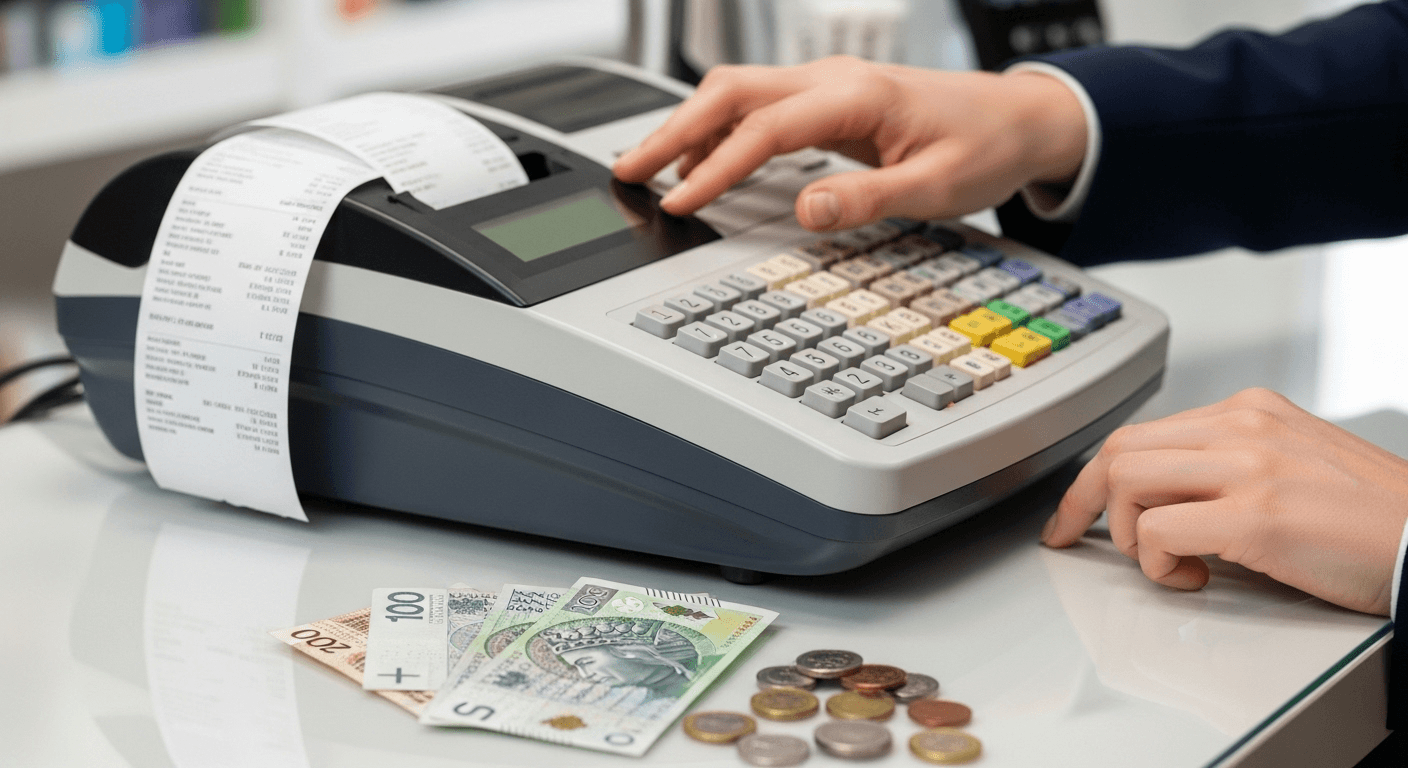
Storing accounting records properly is one of the fundamental obligations of every business owner in Poland. The law requires all businesses, regardless of their size, to keep accounting evidence, stocktaking documents and sales records for a strictly defined period. The purpose of this obligation is to allow later checks of whether taxes were settled correctly, to pursue claims and to resolve any legal or tax disputes.
It is particularly important to store fiscal receipts (paragon) and cash register reports properly, as for many business owners they are the core documentation of their sales. Failure to comply with the rules on archiving documents can have serious legal and financial consequences, so every business owner should know their obligations in this area well. The device itself also needs regular checks – see our article on the cash register technical inspection.
What fiscal receipts are as accounting evidence
Fiscal receipts are a key part of the accounting records of businesses selling at retail. Under the rules in force, sales to private individuals who do not run a business or to flat-rate farmers must, as a rule, be recorded on a cash register (kasa fiskalna) (Article 111(1) of the VAT Act), unless the taxpayer uses an exemption under the Regulation of the Minister of Finance of 17 December 2024 (Journal of Laws (Dz.U.) 2024, item 1902, exemptions until 31 December 2027). The same duty covers prepayments – we explain when to issue a fiscal receipt for an advance payment.
A fiscal document is a document issued using a cash register that bears the fiscal logo and a unique number. For online cash registers it covers the fiscal receipt, the cancelled fiscal receipt, the invoice, the cancelled invoice and the fiscal report
The regulation on cash registers (since 1 July 2025, the Regulation of the Minister of Finance of 25 June 2025, Dz.U. 2025, item 845, § 2(1)) defines fiscal documents precisely, depending on the type of cash register used. For online cash registers, fiscal documents include the fiscal receipt, the cancelled fiscal receipt, the invoice, the cancelled invoice and the fiscal report. For cash registers with an electronic or paper copy record, the list also includes the daily fiscal report, the periodic (including monthly) fiscal report and the closing fiscal report.
Fiscal reports are a special category of fiscal documents. The daily fiscal report, the periodic fiscal report and the closing fiscal report are full or short fiscal reports containing summary data on the value of sales and the amount of tax broken down by tax rate, as well as the value of VAT-exempt sales for a given period.
Fiscal receipts and daily and monthly fiscal reports document sales made by a business owner to private individuals or flat-rate farmers using a cash register. In the KPiR (tax revenue and expense ledger), revenue from such sales is entered on the basis of daily or monthly fiscal reports (§ 11(1)(2) and § 12 of the regulation on keeping the tax revenue and expense ledger, Dz.U. 2025, item 1299)
All these documents are fundamental for keeping accounting records and settling taxes correctly. They are the basis for checking whether sales were recorded correctly and whether VAT was settled properly. Receipts you receive when you buy something are a different matter: since 1 January 2026, a receipt without the buyer's NIP (tax identification number) may document an expense in the KPiR only for purchases of fuel or oils abroad (§ 8(4) of that regulation), while a receipt showing the buyer's NIP for an amount of up to PLN 450 is a simplified invoice (Article 106e(5)(3) of the VAT Act; for taxpayers covered by KSeF (National e-Invoicing System), Article 145n(1)(2) allows such receipts until 31 December 2026). Clients' receipts and simplified invoices are booked by our accounting firm in Warsaw.
Legal basis for storing fiscal receipts
The legal framework for storing fiscal receipts is based on several key acts that complement each other and form a consistent set of obligations for business owners. The main basis is the VAT Act, the Tax Ordinance Act (Ordynacja podatkowa) and the Accounting Act.
Under the VAT Act, taxpayers who record sales using cash registers must keep copies of cash register documents for the period set by tax law, in line with the conditions laid down in the Accounting Act (Article 111(3a)(6) in conjunction with Article 112 of the VAT Act).
The VAT Act requires taxpayers to keep the records kept for tax settlement purposes and all documents related to that settlement until the tax liability becomes time-barred
The Accounting Act sets out in detail how accounting documents must be stored. Under its rules, accounting evidence and stocktaking documents must be kept at the entity in their original form, in a set order adapted to the way the accounting books are kept, divided into reporting periods, in a way that makes them easy to find.
The rules also allow sets of documents to be stored outside the entity, provided they are handed over for safekeeping to another entity providing professional document archiving services. Annual sets of accounting evidence and stocktaking documents must be labelled with the name of their type and with the final years and final numbers in the set.
- Secure all fiscal receipts in proper chronological order
- Label sets of documents with their type and the years they cover
- Ensure easy access to the documents throughout the storage period
- Keep the documents in their original form or as legally recognised copies
- Prepare suitable storage space or use external services
- Introduce access control for archived documents
How long to keep fiscal receipts
A key element of the obligations related to archiving fiscal receipts is determining the correct storage period. That period is set by the limitation period for the tax liability, which is precisely defined in the Tax Ordinance Act.
Under Article 70 § 1 of the Tax Ordinance Act, a tax liability becomes time-barred, as a rule, after 5 years from the end of the calendar year in which the tax payment deadline passed; the limitation period may be suspended or interrupted in the cases set out in the Act. This rule is fundamental for all taxpayers required to keep tax records.
Taxpayers required to keep tax books must store the books and the related documents until the tax liability becomes time-barred, unless the tax acts provide otherwise
In practice, this means that business owners must keep fiscal receipts, as a rule, for 5 years from the end of the calendar year in which the tax payment deadline passed (Article 86 § 1 of the Tax Ordinance Act, Article 112 of the VAT Act). This requirement is also confirmed by the regulation on cash registers, which states that taxpayers keeping records store fiscal documents and copies of fiscal documents, including data from the protected memory of an online cash register, for the period required by the VAT Act and the Tax Ordinance Act (§ 6(1)(7) of the regulation of 25 June 2025). When to issue receipts for payments made after hours is explained in a separate article.
| Type of document | Storage period | Legal basis | How it is counted |
|---|---|---|---|
| Fiscal receipts | 5 years | Tax Ordinance Act (Article 86 § 1, Article 70 § 1) | From the end of the year in which the tax payment deadline passed |
| Daily reports | 5 years | Tax Ordinance Act (Article 86 § 1, Article 70 § 1) | From the end of the year in which the tax payment deadline passed |
| Monthly reports | 5 years | Tax Ordinance Act (Article 86 § 1, Article 70 § 1) | From the end of the year in which the tax payment deadline passed |
| Copies of fiscal documents | 5 years | VAT Act (Article 111(3a)(6), Article 112) | From the end of the year in which the tax payment deadline passed |
A five-year storage period for fiscal receipts is fully justified because these documents are often the only evidence of transactions with private individuals who do not run a business. They make it possible to check whether sales were recorded correctly and, consequently, whether tax was settled properly.
The regulation on cash registers requires taxpayers to ensure access to fiscal documents and data from the protected memory throughout the required storage period, in line with the conditions laid down in the Accounting Act
Conditions for storing fiscal documents
Storing fiscal receipts properly requires meeting a number of detailed technical and organisational conditions. The Accounting Act and implementing regulations set precise standards that must be maintained throughout the archiving period.
The basic requirement is to keep documents in their original form, unless specific rules allow other forms of archiving. Documents must be arranged in a way adapted to how the accounting books are kept, divided into reporting periods.
- Documents must be kept in their original form or as legally permitted copies
- Easy access to the documents must be ensured throughout the archiving period
- Documents should be arranged chronologically and divided into reporting periods
- Sets of documents must be properly labelled with their type and symbols
- The storage location must protect the documents against damage and loss
- Access to the documents should be controlled and limited to authorised persons
The storage system must also make it possible to find specific documents quickly in the event of a tax inspection or other official proceedings. That is why it is important to introduce a suitable system for cataloguing and indexing documents.
The rules allow sets of documents to be stored outside the business, provided they are handed over for safekeeping to a specialised entity providing archiving services
Particular attention should be paid to protecting documents against factors that could damage or destroy them. This covers physical factors such as moisture, temperature and light, as well as protection against unauthorised access or theft.
Consequences of failing to meet archiving obligations
Failing to meet the obligations related to storing fiscal receipts can have serious legal and financial consequences for business owners. The system of sanctions includes various penalties and additional charges that can significantly affect the company's finances.
The basic consequences of storing documents incorrectly follow from the Tax Ordinance Act, specific tax acts and the Fiscal Penal Code (KKS). Failure to keep invoices or proof of purchase of goods is punishable by a fine of up to 180 daily rates (Article 62 § 3 KKS), and failure to keep the books – which the Code defines as including cash register records – in the required place is punishable by a fine of up to 240 daily rates (Article 60 § 2 in conjunction with Article 53 § 21(5) KKS); in minor cases it is a fiscal petty offence. The fine is imposed by a court or by a penalty notice (mandat) – up to five times the minimum wage, i.e. up to PLN 24,030 in 2026 and up to PLN 24,750 from 1 January 2027 (Article 48 § 2 KKS).
A business owner running an online shop did not keep the fiscal receipts from their in-store cash registers for the required five years. A tax inspection revealed that the documents for two years had been destroyed too early. As a result, the tax authority determined the tax base by estimation, which led to a significant additional financial burden for the company, and the failure to keep the documents also exposed the owner to a fine under the Fiscal Penal Code.
Further consequences may include difficulties in appeal proceedings, being unable to prove tax-deductible costs and problems with settling VAT. In extreme cases, the inspection authorities may even reject the entire accounting records.
Being unable to present the required documents during a tax inspection may result in the tax base being determined by estimation (Article 23 § 1 of the Tax Ordinance Act). The estimate should be close to the actual figure (Article 23 § 5), but without documents it is hard to show that the actual turnover was lower
Business owners should also remember the possible civil-law consequences. A lack of proper documentation can make it harder to pursue claims against business partners or to handle complaints about goods or services, and it can also affect how financial institutions assess the company's credibility.
Modern methods of archiving fiscal documents
The development of digital technology gives business owners new options for archiving fiscal receipts and other accounting documents. The law is gradually adapting to what modern technology offers, allowing more efficient document management.
Electronic archiving systems offer a number of advantages over traditional storage of paper documents. Above all, they provide much better protection against the loss of documents, make it possible to search for and access specific items quickly and reduce storage costs.
Electronic systems must ensure data integrity, protection against unauthorised access and the ability to reproduce documents in their original form throughout the required storage period
Modern solutions include scanning paper documents with OCR technology, electronic document management systems and cloud platforms providing secure data storage. It is essential, however, that these solutions comply with the legal requirements for archiving.
- Systems must ensure that archived documents cannot be altered
- It must be possible to verify the authenticity of electronic documents
- Appropriate backup procedures must be put in place
- The system must allow documents to be exported in standard formats
- Access to the system should be protected by user authorisation
- The platform must ensure continuity of operation throughout the archiving period
When choosing an electronic archiving system, business owners should pay particular attention to compliance with data protection rules, the ability to integrate with their existing accounting systems and the availability of technical support throughout the period of use.
Practical aspects of organising a document archive
Organising an archive of fiscal documents effectively requires a well-thought-out approach and suitable organisational procedures. Whatever archiving method you choose – traditional or electronic – it is essential to be systematic and consistent in keeping your records.
The first step in organising an archive is to draw up clear procedures for the flow of documents in the company. These procedures should specify how fiscal receipts are collected, initially sorted, transferred to the archive and checked for completeness.
Another important element is labelling and cataloguing documents properly. Each set of documents should be clearly marked with the period it covers, the type of documents and other relevant information that allows specific items to be found quickly.
It is worth introducing regular checks of the completeness of the archive and of the condition of the documents, especially with traditional archiving. This allows problems to be detected early and remedial action to be taken
In larger companies, it may be advisable to appoint a specific person responsible for managing the document archive. That person should have the necessary knowledge of the legal requirements and the organisational skills needed to run the archive.
It is equally important to provide suitable physical conditions for storing documents. Archive rooms should be dry, well ventilated, protected against access by unauthorised persons and equipped with suitable shelves and cabinets that allow documents to be stored in an orderly way.